FBCCI Administrator seeks waiver of Tk 133 crore in interest
• IFIC Bank’s outstanding dues from Plummy Fashions remain about Tk267 crore
• The bank has already classified it ‘bad loans’
• The bank has filed a case with the Narayanganj Money Loan Court to recover the loan
• The market value of the mortgage assets is much lower to outstanding dues
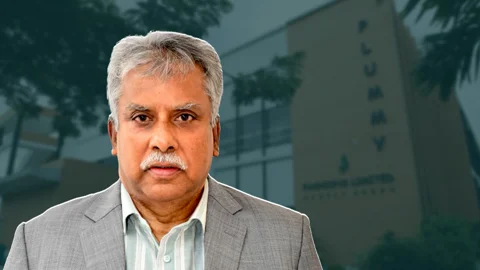
IFIC Bank’s dues from Plummy Fashions Limited in Narayanganj have reached around Tk 267 crore. As it faces financial difficulties, the loan has been classified as “bad/loss” by the bank. Now, the company’s Managing Director and FBCCI administrator Fazlul Hoque has sought waiver of around Tk 133 crore in interest and other charges.
In return, he has proposed to pay around Tk 134 crore in a one-time payment to settle the loan. However, a resolution is pending. On the one hand, Plummy Fashions would like to settle the loan by a negotiated agreement. On the other hand, IFIC Bank has gone to court to recover the dues. In a case filed by the bank, it has claimed around Tk 262 crore and Tk 52 lakh. As a result, whether the proposed settlement will be implemented depends on the bank’s decision.
Plummy Fashions’ factory is located in Uttar Narsingpur of Fatullah, Narayanganj. The company owes the bank around Tk 266 crore and Tk 96 lakh. Of this, a waiver of around Tk 132 crore and Tk 93 lakh has been sought, covering interest accrued during litigation, interest on suspense and interest transferred as income.
The remaining Tk 134 crore and Tk 3 lakh has been proposed to be paid in a one-time payment to settle the loan. At a board meeting held on August 10, a decision was taken to repay the principal amount of the loan by selling the factory.
The documents cite several reasons behind Plummy Fashions’ financial difficulties. The company had invested more than expected on setting up an environmentally-friendly factory. However, it did not gain the expected premium from buyers. The situation was aggravated by the global economic downturn.
Because of the downturn, garment orders were cut in international markets. As a result, the company’s business revenue continued to fall. Its export and business transactions through IFIC Bank have been suspended since November 2024. Eventually, on June 30, 2025, Plummy Fashions’ loan was classified as “bad/loss.”
Amid the crisis, there has been an initiative to change the ownership structure. On June 16, Plummy Fashions sought a no-objection certificate (NOC) from IFIC Bank to transfer its shares to new buyers. However, the bank rejected the application on June 22. As the situation became more complicated, the board decided to sell the factory and repay the principal amount of the loan.
Behind the Crisis
Although Plummy Fashions has a reputation of being an environmentally-friendly green factory, questions have now arisen over the company’s financial capacity. According to the documents, the company has spent more than expected to set up the green factory. However, it has failed to gain the expected benefits from the additional investment. It could not secure the premium from buyers for environmentally friendly production.
At the same time, the global economic downturn has affected the apparel sector. Orders from international markets have declined. However, the cost of production and the instalments from the bank have remained unchanged, with revenue continuing to fall. The pressure from both sides has caused a cash-flow crisis. At one point, it became difficult for the company to make regular instalment payments.
The situation became more difficult in November 2024. Since then, the company’s exports and other business dealings through IFIC Bank have been suspended. This has further disrupted its normal business operations.
Due to the prolonged crisis, the bank has classified the company’s loan as “bad/loss” on June 30, 2025. In accordance with banking sector rules, this is the highest classification for a defaulted loan. As a result of the classification, efforts have been made to settle the loan.
Plummy Fashions was once regarded as a positive example of the country’s apparel industry for its environmentally-friendly production system. However, after becoming a major loan defaulter, questions have now been raised over the company’s survival and its previous reputation.
Initiative to Sell the Factory
To address the crisis, Plummy Fashions initially attempted to change its ownership structure. On June 16, it formally sought an NOC from IFIC Bank. The bank rejected the application on June 22. As a result, the initiative to resolve the crisis through a change in ownership has been closed.
Plummy Fashions’ board decided to sell the entire factory as an alternative solution. The decision was taken at a board meeting held on August 10.
According to the decision, the proceeds from the sale of the factory would be used to repay the principal amount of the bank loan in a one-time payment. The company wrote to IFIC Bank the following day.
The letter stated that an initiative concerning the sale of the factory had already been completed. It also mentioned a plan to settle the entire loan by repaying the principal from the sale proceeds and seeking a waiver of interest and other charges.
However, the process of selling the factory has not yet been completed. If it is not completed, the proposed settlement plan could face uncertainty. Questions have also arisen over management of the factory’s future operations.
Bank’s Lawsuit
IFIC Bank is proceeding on two fronts — a settlement proposal on one hand and legal action on the other. The bank has gone to court to recover the loan. On July 8, it has filed a case against Plummy Fashions with the Narayanganj Artha Rin Adalat. The case number is 173/2026. The bank has claimed around Tk 262 crore and Tk 52 lakh in the case.
There is a significant gap between the amount claimed by the bank in court and the amount proposed for repayment by the company. Plummy Fashions has proposed to settle the loan by paying around Tk 134 crore in a one-time payment. In contrast, the bank has sought nearly twice that amount through the court. As negotiations and legal proceedings are proceeding simultaneously, it is difficult to say at this point what the final outcome will be.
According to bank documents, if around Tk 134 crore can be recovered outside court under the proposed settlement, it would also have a positive impact on the bank’s overall non-performing loan ratio. However, if the settlement fails, the bank will have to proceed through litigation, which could be a time-consuming and costly process.
Questions Over the Value of Mortgaged Assets
There is also a significant gap concerning the value of the assets mortgaged against Plummy Fashions’ loan. According to the bank’s valuation, the market value of the company’s 237.50 decimals of land and buildings is around Tk 49 crore and Tk 95 lakh. The market value of the machinery at the factory is around Tk 72 crore and Tk 54 lakh. The total market value of the mortgaged land, buildings and machinery is around Tk 122 crore and Tk 50 lakh.
While the bank’s outstanding dues are around Tk 267 crore, the market value of the mortgaged assets is approximately half of the outstanding amount. Not only the market value but also the amount that could be recovered from these assets under a quick-sale or distress situation would be lower.
According to the bank’s calculations, the distress value or quick-sale value of the mortgaged assets is Tk 94 crore and Tk 96 lakh. This gap has made the decision difficult for the bank.
As the value of the mortgaged assets is much lower than the outstanding dues, it would be difficult to recover the entire amount even by selling the assets through court proceedings. Therefore, the bank authorities have yet to make a final decision on whether to pursue lengthy legal proceedings or settle the loan by recovering a lump-sum payment as proposed by the company.
Full Recovery or Waiver?
For IFIC Bank, the issue is not simply a matter of a single loan account. It involves a number of complex factors, including the amount of non-performing loans, the actual value of the mortgaged assets, the time and cost of conducting litigation and ultimately how much money can realistically be recovered.
The bank’s total outstanding dues from Plummy Fashions stand at Tk 266 crore and Tk 96 lakh. Of this, a waiver of around Tk 132 crore and Tk 93 lakh in interest and related charges has been sought. In return, the company has proposed to pay Tk 134 crore and Tk 3 lakh in a one-time payment.
If the proposal is implemented, the bank would have to waive a substantial portion of its dues. However, if the proposed amount can be recovered in a single payment, it would significantly reduce the impact of the defaulted loan.
On the other hand, pursuing the case through court and recovering money by selling the mortgaged assets could take considerable time. As the distress value of the mortgaged assets is only Tk 94 crore and Tk 96 lakh, even selling the assets through court proceedings may not allow the bank to recover its full dues. Therefore, the bank authorities are analysing which option would be more beneficial — a settlement or litigation.
Awaiting a Decision
Plummy Fashions has proposed a waiver of around Tk 133 crore in interest and other charges and a one-time payment of around Tk 134 crore to settle the loan. At the same time, IFIC Bank has filed a case in court to recover the dues. The question now is whether the loan will be settled by recovering the proposed lump-sum payment or whether the ongoing legal process will continue.
If the agreement to sell the factory is implemented, it could allow the bank to recover its dues more quickly. However, if the sale process is not completed and the proposed amount is not recovered, the settlement of the loan could once again face uncertainty. The significant gap between the market value and distress value of the mortgaged assets and the bank’s total outstanding dues has complicated the issue.